
Can You Get Life Insurance With No Medical Exam?
 Posted in No Exam last updated on October 28, 2026
Yes, you can get life insurance with no medical exam and no waiting period. Depending on your age, health, and the carrier, you might qualify for $500K, a million, or even more in coverage without ever setting foot in a clinic for blood work.
In fact, many life insurance companies now offer accelerated underwriting programs that allow qualifying applicants to skip the traditional medical exam altogether. Some applicants can even receive a decision within minutes.
For instance, if you’re anywhere from 20 to 60 years old, carriers like Banner Life can sometimes fast-track approval for up to $4 million in coverage with no exam. Even if you’re between 61 and 70, you can still find no-exam options for up to $500,000.
But here’s something worth understanding before you apply:
Not all no-exam life insurance policies work the same way. Some offer the same competitive rates and coverage options as traditionally underwritten policies, while others have higher premiums, lower coverage limits, or restrictions on when the full death benefit becomes available. The key is understanding which policy type makes the most sense for your situation.
In this guide, we’ll explain how no-exam life insurance works, how much coverage you can qualify for, which insurance companies offer it, and what to look for when comparing policies.
Key Takeaways
- You can qualify for substantial life insurance coverage without a medical exam. Some companies offer accelerated underwriting for $1 million, $2 million, or more.
- No medical exam doesn’t mean guaranteed approval. Insurance companies may still review your health history, prescription records, and other information.
- No-exam life insurance doesn’t always cost more. Qualifying applicants may receive the same rate classifications available through traditional underwriting.
- Some policies provide the full death benefit once coverage begins, while others have graded death benefits during the first few years.
- Comparing insurance companies matters because underwriting requirements, coverage limits, and premiums vary from one carrier to another.
Table of Contents
- How Does Life Insurance Without a Medical Exam Work?
- What Are the Different Types of No-Exam Life Insurance?
- Can You Get Life Insurance With No Medical Exam and No Waiting Period?
- How Much Life Insurance Can You Get Without a Medical Exam?
- How Much Does Life Insurance With No Medical Exam Cost?
- Which Life Insurance Companies Offer No-Medical-Exam Coverage?
- Can You Get No-Exam Life Insurance With Health Conditions?
- What If You Don’t Qualify for No-Exam Life Insurance?
- No Exam Life Insurance for Seniors
- How Do You Compare No-Exam Life Insurance Quotes?
- FAQs
How Does Life Insurance Without a Medical Exam Work?
Back in the day, getting life insurance meant scheduling a medical exam, having your blood drawn, and waiting for the insurance company to review your results. That’s no longer the case for many applicants.
Today, no medical exam life insurance allows qualifying applicants to get coverage without going through that traditional process. Instead of sending a medical professional to your home or office, the insurance company may review information that’s already available, including your health history, prescription records, driving history, and previous insurance applications.
You’ll still need to answer questions about your health and lifestyle, but if the company has enough information to evaluate your application, you may qualify without completing any medical tests.
Here’s how the process generally works:
- Choose your coverage: Decide how much life insurance you need and whether term or permanent coverage makes the most sense.
- Complete an application: Answer questions about your health, medications, lifestyle, and financial situation.
- The insurance company reviews your information: Depending on the underwriting program, the company may use electronic medical records and other permitted data to evaluate your application.
- Receive an underwriting decision: You may be approved without an exam, asked for additional information, or referred for traditional underwriting.
- Accept your policy: Once approved, you’ll review the final offer and complete any outstanding requirements before your coverage becomes effective.
Some applicants can complete the entire process online. Others may need to provide additional medical information before the insurance company makes a final decision.
One thing I want to make clear: no medical exam doesn’t mean no underwriting. The insurance company still evaluates your health and other risk factors. The difference is how it collects the information needed to make its decision. In many cases, that makes applying for life insurance much more convenient.
What Are the Different Types of No-Exam Life Insurance?
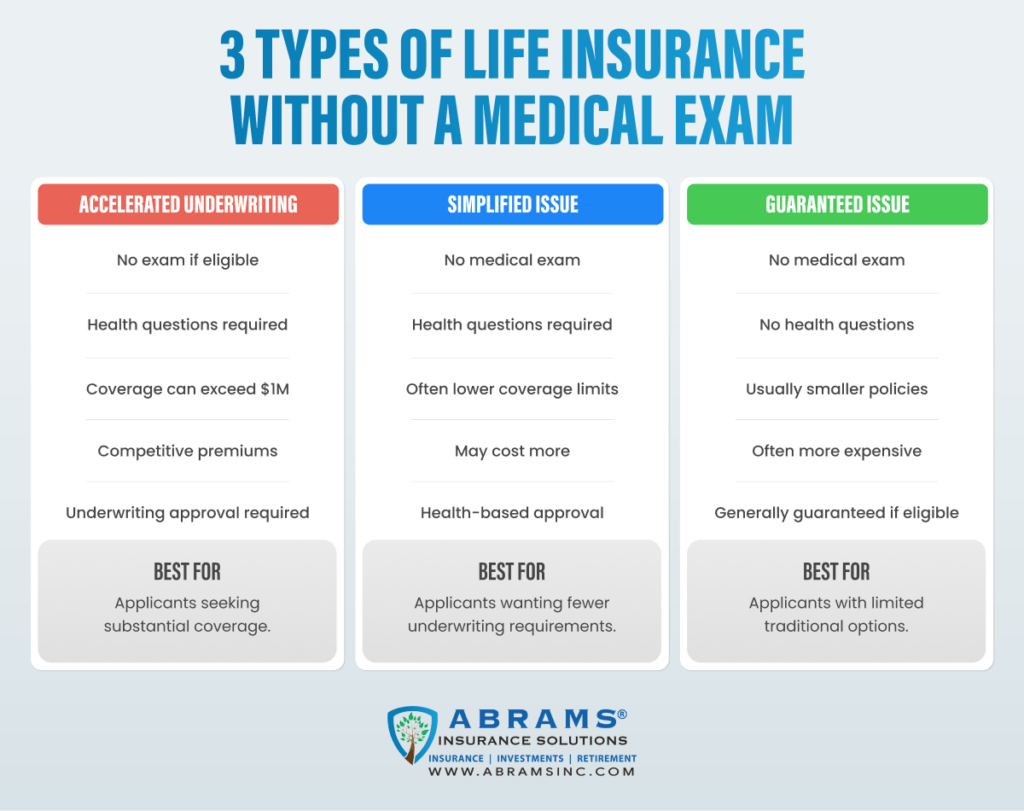
There are three main types of no-exam underwriting: Accelerated, simplified issue, and Guaranteed issue. Understanding the differences between these types can help you avoid paying more than necessary or buying a policy with unexpected restrictions.
Accelerated Underwriting
Accelerated underwriting is generally the first option I’d recommend exploring, especially if you’re reasonably healthy and looking for a larger amount of life insurance.
With this type of underwriting, the insurance company uses available medical and electronic information to determine whether you qualify without a traditional exam.
The biggest advantage is that you don’t necessarily have to buy a special, more expensive no-exam policy. You may qualify for the same term or permanent life insurance product and underwriting classification available to someone who completes a medical exam.
For example, let’s say you’re 40 years old, in good health, and looking for a $1 million, 20-year term life insurance policy. Depending on the insurance company, you may be able to complete the application online and receive approval without blood work or a medical appointment. And if you qualify for a preferred underwriting classification, you may receive the same rate the company offers through its traditional underwriting process.
However, not everyone qualifies. If the insurance company needs more information, it may request medical records or require an exam.
Click here for more information on Instant Life Insurance
Simplified Issue Life Insurance
Simplified issue life insurance is another option for people who want coverage without going through a traditional medical exam.
These policies typically require you to answer health questions, but the application process is often less extensive than traditional underwriting. The tradeoff is that coverage amounts may be more limited, and premiums can be higher than comparable fully underwritten policies.
Simplified issue can make sense for certain applicants, particularly when the available accelerated underwriting programs aren’t a good fit. However, I wouldn’t automatically choose simplified issue simply because it doesn’t require an exam.
It’s worth comparing the actual premiums and policy benefits first.
Guaranteed Issue Life Insurance
Guaranteed issue life insurance works differently. These policies generally don’t require a medical exam or health questions, and eligible applicants can obtain coverage regardless of their medical history.
This can help someone with significant health problems who has difficulty qualifying for traditional life insurance, but it has important limitations.
Guaranteed issue policies usually offer relatively small death benefits, often designed to help cover funeral expenses and other final costs. Premiums can also be expensive relative to the coverage provided.
More importantly, many guaranteed issue policies have a graded death benefit. This means you may not be able to receive the full death benefit for certain causes of death during the first two or three years.
For most applicants who can qualify for traditional or accelerated underwriting, I’d explore those options before considering guaranteed issue coverage.
Can You Get Life Insurance With No Medical Exam and No Waiting Period?
Yes. Some no-exam life insurance policies provide the full death benefit as soon as coverage becomes effective, while others have restrictions during the first few years.
The important thing is understanding that no medical exam and no waiting period are two different things.
For example, if you qualify for a traditional term life insurance policy through accelerated underwriting, you generally receive the full death benefit once coverage takes effect, subject to the policy’s terms and exclusions.
Guaranteed issue life insurance, on the other hand, often has a graded death benefit during the first two or three years.
Let’s say you purchase a $25,000 guaranteed issue policy with a two-year graded death benefit. If you pass away from an illness during those first two years, the insurance company may only refund the premiums you’ve paid, plus any interest specified in the policy.
However, if you die after the graded period ends, the full contractual death benefit would generally become payable for a covered death.
There are also a few other provisions worth understanding:
| Provision | What it means |
|---|---|
| Policy effective date | The date your insurance coverage officially begins |
| Graded death benefit | Limits the benefit payable for certain deaths during an initial period |
| Contestability period | Allows the insurer to investigate and potentially contest claims under applicable law |
| Suicide exclusion | May limit the benefit payable for suicide during an initial period |
Don’t confuse the contestability period with a waiting period. They are not the same thing.
If you’re specifically looking for no-waiting-period life insurance, focus on policies that provide the full contractual death benefit once coverage becomes effective, rather than assuming every policy advertised as no-exam offers that protection.
How Much Life Insurance Can You Get Without a Medical Exam?
You may qualify for significantly more coverage than you think.
In the past, no-exam life insurance was often associated with smaller policies, typically designed for final expenses or basic family protection. That has changed considerably.
Today, some insurance companies offer accelerated underwriting for several million dollars in coverage, depending on your age, health, financial situation, and the specific policy.
For example, Pacific Life currently describes a no-exam underwriting pathway for qualifying applicants ages 18–60 seeking up to $3 million of PL Promise Term coverage. Lincoln Financial also offers lab-free consideration for eligible applicants ages 18–60 seeking up to $2.5 million through certain programs.
Here’s how different coverage amounts might fit your needs.
$500,000 Life Insurance Without a Medical Exam
A $500,000 policy may be enough to replace several years of income, cover a mortgage, or support your family financially. If you’re relatively healthy, several insurance companies may offer this amount through accelerated underwriting.
$1 Million Life Insurance Without a Medical Exam
A million dollars may sound like a substantial amount of coverage, but it can make sense for families with higher incomes, young children, mortgages, and other long-term financial obligations. For example, someone earning $150,000 annually may want enough coverage to replace several years of income while also paying off debts and funding future education expenses.
Several companies offer accelerated underwriting for qualifying applicants seeking this amount.
$2 Million or More Without a Medical Exam
If you’re a high-income professional, business owner, or someone with significant financial obligations, you may need considerably more coverage. And qualifying for a larger death benefit doesn’t automatically mean you’ll need a medical exam.
Some insurers offer accelerated underwriting for $2 million or more, although you’ll still need to qualify medically and financially.
How Much Does Life Insurance With No Medical Exam Cost?
No-exam life insurance can be surprisingly affordable, particularly for younger, healthy applicants purchasing term insurance. And contrary to what many people assume, skipping the medical exam doesn’t automatically mean paying a higher premium.
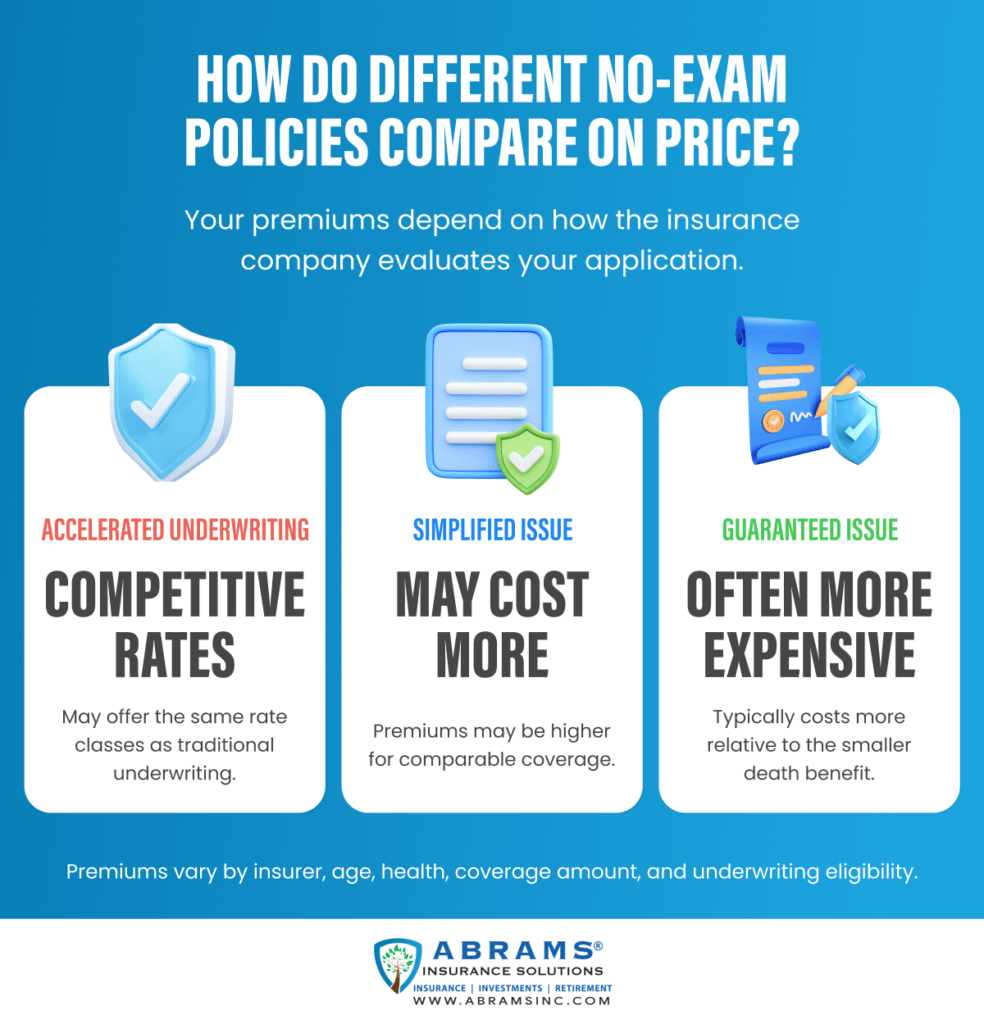
With accelerated underwriting, qualifying applicants may receive the same underwriting rate classifications available through traditional underwriting.
Your actual cost depends on several factors, including your age, health, nicotine use, coverage amount, term length, policy type, and insurance company.
For example, a healthy 35-year-old applying for a $500,000, 20-year term policy will generally pay less than a 55-year-old applying for the same coverage.
The insurance company you choose can also make a significant difference. One carrier may offer a preferred rate classification for your particular health profile, while another may evaluate the same medical history differently.
That’s why I recommend comparing several insurance companies rather than choosing the first quote you see.
Does No-Exam Life Insurance Cost More?
Not necessarily. If you qualify through accelerated underwriting, your premiums may be comparable to those available through traditional underwriting.
Simplified issue and guaranteed issue policies, however, can cost more per dollar of coverage because the insurance company collects less medical information.
The rate you see when comparing policies is still an estimate until underwriting is complete.
Which Life Insurance Companies Offer No-Medical-Exam Coverage?
Several reputable insurance companies offer life insurance without a medical exam, but the right choice depends on your age, health, coverage needs, and the type of policy you’re looking for.
If you’re relatively healthy and want a large term life insurance policy, I generally recommend comparing companies that offer accelerated underwriting.
Here are a few worth considering:
Banner Life
Banner Life is often one of the more competitively priced carriers for healthy individuals seeking term life insurance. It also offers accelerated underwriting opportunities for qualifying applicants seeking substantial coverage.
As discussed in our $1 million life insurance guide, its no-exam programs can be particularly attractive for eligible applicants who want competitive pricing and a streamlined application.
However, underwriting eligibility depends on your age, health, coverage amount, and other requirements.
Pacific Life
Pacific Life is another company worth considering, especially if you’re looking for $1 million or more in term coverage. Its Pacific Accelerated Life+ (PAL+) program currently offers a no-exam pathway for qualifying applicants ages 18–60 seeking up to $3 million in PL Promise Term coverage. That doesn’t mean everyone will qualify for the full amount without an exam. The company still reviews your application and may request additional information or traditional underwriting.
Assurity
Assurity has an Accelerated Underwriting program for policies up to $1,000,000, depending on your age. With this program, you can get a term life insurance policy with potentially instant online approval and immediate coverage. To qualify for instant approval, you must be in good health with only minor health conditions.
Click here to view Assurity Rates and Apply Online
Lincoln Financial
Lincoln Financial offers streamlined underwriting for several types of life insurance, including term and certain permanent policies. Its published guidelines describe lab-free consideration for qualifying applicants ages 18–60 seeking up to $2.5 million through eligible application processes. Lincoln may be worth comparing if you’re interested in term coverage or want to explore permanent insurance options.
Other Insurance Companies
Depending on your situation, companies such as Protective Life, American National, and SBLI may also be worth evaluating. However, the availability of no-exam underwriting varies by product, application method, and applicant.
I wouldn’t automatically recommend one company over another without first understanding your needs.
For example, a healthy 35-year-old seeking $1 million in term insurance may have very different options from a 55-year-old taking several medications.
Important: If you have moderate or significant health conditions, I recommend speaking with an independent advisor before submitting applications. Choosing the right carrier can help you avoid unnecessary declines and improve your chances of receiving a favorable offer.
Can You Get No-Exam Life Insurance With Health Conditions?
Yes. Having a medical condition doesn’t automatically disqualify you from getting life insurance without a medical exam.
Depending on the insurance company, applicants with controlled high blood pressure, elevated cholesterol, mild asthma, or certain other manageable conditions may still qualify for accelerated underwriting.
However, insurers don’t evaluate medical conditions based on the diagnosis alone. They may also consider how long you’ve had the condition, what medications you take, whether it’s well controlled, and whether you’ve experienced any complications.
For example, someone taking medication for high blood pressure with consistently good readings may have different underwriting options than someone whose blood pressure remains uncontrolled.
Additionally, two insurance companies may evaluate the same applicant differently. If you have a medical condition, choosing a company whose underwriting guidelines fit your health history may matter more than finding the lowest advertised premium.
For more information check out our articles on getting life insurance with pre-existing health conditions.
What If You Don’t Qualify for No-Exam Life Insurance?
If you don’t qualify for accelerated underwriting, you may still be able to get life insurance. In many cases, it simply means the insurance company needs more medical information before deciding.
You may still be able to obtain the same coverage amount through traditional underwriting. You could also consider another insurance company, apply for a smaller amount, or explore a different type of policy.
For example, someone who doesn’t qualify for $1 million without an exam might still qualify for the full amount after completing a medical exam. Another insurer may even offer a no-exam option that better fits their circumstances.
The point is that avoiding a medical exam shouldn’t matter more than getting suitable coverage at a competitive price.
How Quickly Can You Get Approved?
Some applicants receive an underwriting decision within minutes, while others may wait several days or longer. It depends on the insurance company and whether it needs additional information. If you qualify for accelerated underwriting, you may receive approval without scheduling a physical exam or providing blood samples.
Keep in mind that receiving an approval isn’t necessarily the same as having active coverage. Your policy must become effective according to its terms, which may require accepting the offer, completing signatures, and satisfying payment requirements. So before assuming you’re covered, confirm the policy’s effective date.
No Exam Life Insurance for Seniors
One of the most common no-exam options for seniors is final expense life insurance, also known as burial insurance. Final expense insurance is usually a type of whole life insurance, meaning the coverage can last your entire life as long as you pay the required premiums. Most people purchase these policies to help their families cover funeral expenses, burial or cremation costs, and any outstanding medical bills.
Because the death benefits are limited (such as $5,000 to $25,000), the offering companies don’t do extensive underwriting. They skip the medical exam but still ask some medical questions on the application.
While traditional whole life insurance policies can build cash value over time, final expense policies generally aren’t designed to build significant cash value. Their primary purpose is to provide a modest death benefit when your family needs it.
One option worth considering is the Heritage Plan from Guarantee Trust Life.
We’ve put together an in-depth review of the Heritage Plan, including how it works and who might benefit from it in the guide linked above. This policy is designed for applicants ages 40 to 90 and has a simplified application with just five qualifying health questions. Eligible applicants may even receive an approval decision almost immediately.
How Do You Compare No-Exam Life Insurance Quotes?
When comparing policies, don’t focus only on the monthly premium. Start by making sure you’re comparing the same coverage amount and policy duration. A $500,000, 20-year term policy isn’t directly comparable to a $500,000 permanent policy. They serve different purposes and cost differently.
Next, review the insurance company’s underwriting requirements, financial strength, available rate classifications, and policy features. If you’re considering term life insurance, conversion options may also be worth reviewing.
And if you’re looking for coverage without a waiting period, verify exactly when the full death benefit kicks in. The company offering the lowest initial quote isn’t always the company that will offer you the lowest final premium.
Finally, when applying online, avoid submitting applications to multiple companies at once. We at Abrams Insurance work with more than 80 life insurance carriers, so we will make sure you find the single option best suited for your specific situation and needs.
Compare No Exam Life Insurance Rates Without Talking to an Agent
Compare Banner Life rates side-by-side and check your no-exam eligibility in minutes. If you’re healthy, you can skip the agent call and complete the entire process online.
Approval, premiums, coverage limits, underwriting requirements, and policy availability vary by insurer, state, and applicant.
Conclusion
Getting life insurance without a medical exam is easier than it used to be, and qualifying applicants may be able to obtain substantial coverage at competitive rates. But having the right strategy still matters.
Start by determining how much coverage you actually need. Then compare insurance companies based on your age, health, budget, and underwriting options.
Avoiding a medical exam is certainly convenient, but it shouldn’t be the deciding factor. The real goal is to protect your family with the right amount of life insurance at a price that fits your budget.
FAQs
Can You Get Life Insurance Without a Medical Exam or Health Questions?
Yes. Guaranteed issue life insurance generally doesn’t require a health questionnaire or a medical exam. However, coverage amounts are usually smaller, premiums may be higher, and graded death benefits often apply.
Can You Get a $1 Million Life Insurance Policy Without an Exam?
Yes. Several insurers offer accelerated underwriting for qualifying applicants seeking $1 million or more in coverage. Eligibility depends on your age, health history, financial justification, and the insurance company’s requirements.
Can You Get Life Insurance Without Blood Work?
Yes. Applicants who qualify for accelerated underwriting may obtain life insurance without blood or urine testing. However, the insurance company may still review medical records and request additional information.
What Happens If You’re Denied No-Exam Life Insurance?
A decline from one insurer doesn’t automatically mean you can’t obtain coverage elsewhere. Another company may have different underwriting guidelines, or you may qualify through traditional underwriting or another policy type.


4 Comments
Marjie
Please call me at xx between 10 am and 4 pm tomorrow. I
am nterested in A $1M mo lapse GUL insurance policy. I am a 74 year old female willing to take medical exam, healthy, no meds, tobscco, drugs.
Chris Abrams
Hi Marjie. I'll call you tomorrow as requested or feel free to reach out to me at 858-703-6178.
Todd
I dont want any calls i just am looking for $100.000 term 10 year life I am 63 5.10 178 lbs I am in excellent health I dont smoke I am not looking to pay an arm and a leg and I dont like needles
Chris Abrams
Hi Todd. If you want a quick and easy life insurance policy without an exam, you can apply online here: https://agents.ethoslife.com/invite/cded2